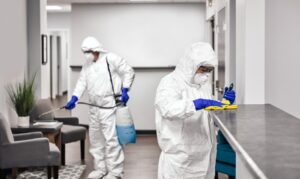
On a large commercial loss, like a flooded ground floor, a sprinkler failure across several floors, or hurricane damage to a multi-building property, the restoration work and the insurance claim move side by side. Here’s how it typically works and how property owners and managers can keep both on track. (General information, not insurance or legal advice.)
1. Mitigation Comes First
Most commercial policies expect the owner to take reasonable steps to prevent further damage. That means stopping the water and starting extraction and drying right away, not waiting for an adjuster’s visit. Delays can increase the loss and complicate the claim.
2. Documentation Drives the Claim
- Photos and video before, during, and after
- Moisture maps and daily drying logs
- Source of loss, clearly identified
- Equipment counts and labor by area and day
- Itemized scope and invoices
3. Working With the Adjuster
On large losses, the carrier often assigns a large-loss adjuster. A good restoration company communicates directly with them, shares documentation as the job progresses, and explains scope changes as they come up, so there are fewer surprises at the end.
4. Mold and Coverage Limits
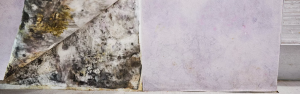
If water turns into mold, coverage may be limited depending on the policy and cause. Fast drying is the best protection. When remediation is needed, licensed work and clear documentation help support the claim.
5. Business Interruption
Many commercial policies include business interruption coverage. Restoration timelines and documentation of when areas were unusable can matter for those claims, so ask your restoration company to track them.
Choosing a Restoration Partner for Large Losses
- Enough equipment on hand for the size of the loss
- Proper licensing (in Florida, mold remediation over 10 square feet requires a state license) and insurance
- Experience on large and multi-unit projects
- Daily reporting you can share with the adjuster
FL Cleanup has completed large projects including a 40+ unit hurricane flood and mold job and work in hospital settings, with $1 million general liability and Florida mold licenses (MRSA4035, MRSR4158). See our large loss response, the case study, or call 877-224-2532.